BoG proposes 30-day liquidity buffer for banks, invites public input
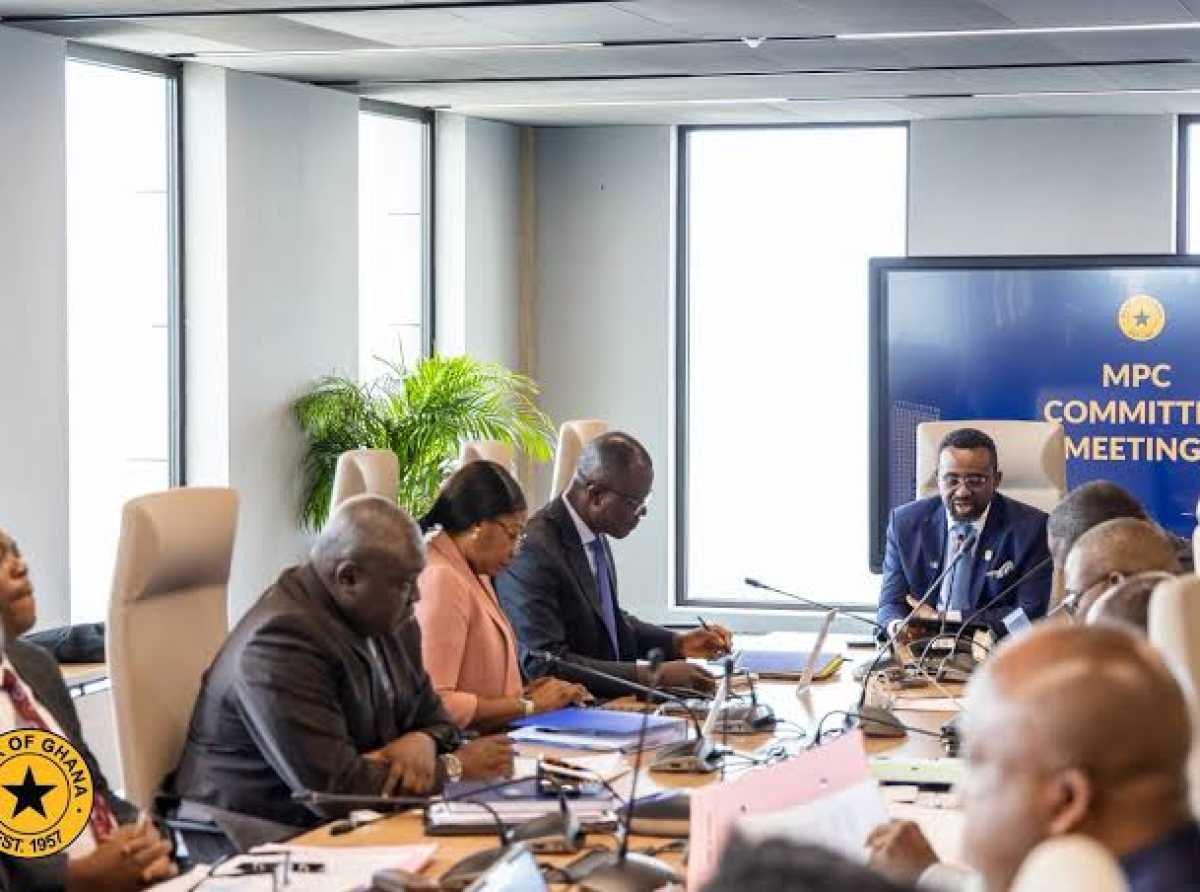
The Bank of Ghana (BoG) is preparing to introduce a Liquidity Coverage Ratio (LCR) requirement for banks as part of efforts to strengthen liquidity risk management and improve the banking sector’s ability to withstand financial shocks.
The central bank has invited banks, industry stakeholders and members of the general public to submit comments on the proposed Liquidity Coverage Ratio Directive before it is finalised.
The consultation is being conducted in accordance with the Bank of Ghana’s Procedures for Issuance of Directives, 2020.
Under the proposed framework, banks would be required to maintain sufficient high-quality liquid assets to cover their liquidity needs during a period of significant financial stress lasting 30 calendar days.
The requirement is designed to ensure that banks can meet their short-term financial obligations even when faced with funding pressures, unexpected cash outflows or disruptions in financial markets.
The proposed directive would also establish a prudential benchmark for evaluating banks’ liquidity buffers and their capacity to withstand sudden withdrawals and other liquidity-related pressures.
The Bank of Ghana has set November 30, 2026, as the deadline for submitting comments on the proposed Liquidity Coverage Ratio Directive.
Interested stakeholders are expected to send their submissions by email to
The central bank has indicated that it will consider all material comments received during the consultation process and provide written explanations outlining how the submissions were addressed.
The explanations will cover whether the comments were incorporated into the final directive.
The consultation provides banks and other interested parties with an opportunity to identify potential implementation challenges, raise concerns and recommend adjustments before the proposed rules are finalised.
The feedback process is expected to help the regulator assess the practical implications of the new requirements and ensure that the final framework supports effective liquidity management across the banking industry.
The proposed Liquidity Coverage Ratio requirement forms part of the Bank of Ghana’s broader efforts to strengthen risk management practices and improve the resilience of the financial sector.
Liquidity risk arises when a bank is unable to meet its financial obligations as they fall due without incurring unacceptable losses. Maintaining sufficient liquid assets helps banks manage unexpected cash demands and reduces their vulnerability during periods of financial uncertainty.
Under an LCR framework, banks are generally expected to hold enough high-quality liquid assets to cover projected net cash outflows over a 30-day stress period.
The proposed requirement could therefore influence how banks manage their treasury operations, allocate funds, plan for liquidity needs and determine the composition of assets held to satisfy regulatory standards.
However, the precise obligations and potential effects on individual banks will depend on the final directive and the specific requirements adopted by the central bank.
Alongside the proposed liquidity rules, the Bank of Ghana has outlined a Credit Risk Management Directive intended to strengthen banks’ approaches to assessing and managing lending risks.
The proposed credit-risk framework is expected to complement the Non-Performing Loan Notice issued by the central bank last year.
It is designed to cover the entire lending process, including credit origination, administration, monitoring, measurement and recovery.
These measures address a different but equally important aspect of banking-sector stability. While the Liquidity Coverage Ratio focuses on banks’ ability to meet short-term financial obligations during periods of stress, the credit-risk framework concentrates on the management of risks associated with lending and loan repayment.
Together, the proposed measures seek to improve banks’ ability to manage financial risks, maintain sound balance sheets and withstand adverse economic conditions.
The introduction of the proposed LCR requirement could prompt banks to review their liquidity management strategies, treasury operations and holdings of high-quality liquid assets.
Depending on the final rules, institutions may need to adjust their funding plans and asset portfolios to ensure they can meet the required liquidity thresholds.
For the banking industry, the consultation period offers an opportunity to provide feedback on implementation challenges and the potential operational implications of the framework.
The final directive will determine how the requirements are applied and what adjustments banks may need to make to comply.
The Bank of Ghana’s initiative forms part of ongoing regulatory efforts to reinforce prudential oversight and strengthen the capacity of financial institutions to manage liquidity and credit risks.
Stakeholders have until November 30, 2026, to submit their comments for consideration before the proposed Liquidity Coverage Ratio Directive is finalised.

Aikines Anyomi
News
Food
Politics
Technology
About Us
Download Our Mobile App

